
Strategic Retirement Planning
The Retirement Asset Hiding in Plain Sight
How Your Home Equity Could Help You Enjoy More of Your Money Today, Preserve Your Assets Longer and Create a More Intentional Legacy
Meanwhile, one of their largest assets may be sitting right underneath them: their home equity.
For the right homeowner, strategically incorporating a reverse mortgage into a broader retirement and estate plan could change that equation. Instead of viewing home equity as money that can only be accessed after selling the home—or after death—what if you considered putting some of that equity to work while you’re still alive?
Your Home Is More Than a Place to Live
Most retirees understand diversification when it comes to investments. They may own stocks, bonds, mutual funds, real estate, IRAs, Roth IRAs and other assets.
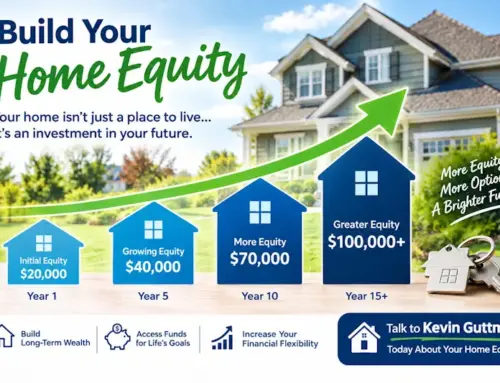
Yet home equity is often treated differently. A homeowner may have $500,000, $1 million or more in equity and never consider how that asset might fit into their overall retirement strategy.
A reverse mortgage can potentially turn a portion of that otherwise illiquid equity into accessible funds without requiring you to sell your home. And with a reverse mortgage, mandatory monthly principal and interest mortgage payments are optional, provided you continue to meet the loan requirements.
Note: You remain responsible for property taxes, homeowners insurance, maintenance, applicable HOA charges and other property obligations.
That flexibility creates some interesting planning opportunities:
1
Preserve and Potentially Prolong Your Investment Assets
One of the biggest retirement risks is having to sell investments at the wrong time. Imagine the stock market drops substantially and you still need $60,000 that year for living expenses. Without another source of funds, you may have to sell investments while they’re down.
That can lock in losses and leave fewer dollars invested to participate in a future recovery. A reverse mortgage line of credit may provide another source of liquidity. Instead of automatically selling investments during a significant market decline, you could potentially use available reverse mortgage proceeds for some expenses, giving your investments more time to recover.
The objective isn’t to predict the market. It’s to have more than one bucket of money available when you need it.
2
Allow More of Your Investments to Continue Working
Consider a homeowner with substantial equity in a paid-off home as well as money in retirement accounts. If every dollar needed for retirement comes from investment accounts, those withdrawals reduce the amount of capital that remains invested.
Home equity provides another potential source. By strategically accessing home equity, a retiree may be able to leave more investment assets invested for longer periods. That doesn’t guarantee better investment performance—markets can rise or fall—but it gives you something retirees often underestimate: Flexibility.
And flexibility can be extremely valuable during a retirement that could last 20, 30 or even 40 years.
3
Have More Money Available to Enjoy Life—Sooner Rather Than Later
There’s another side of retirement planning that doesn’t show up on a spreadsheet: Time.
At 65, you may be able to travel, hike, play golf, visit grandchildren and experience things that may become more difficult at 85. Yet many retirees spend the early years of retirement being extremely cautious with money because they’re afraid of running out, while substantial equity sits unused in their home.
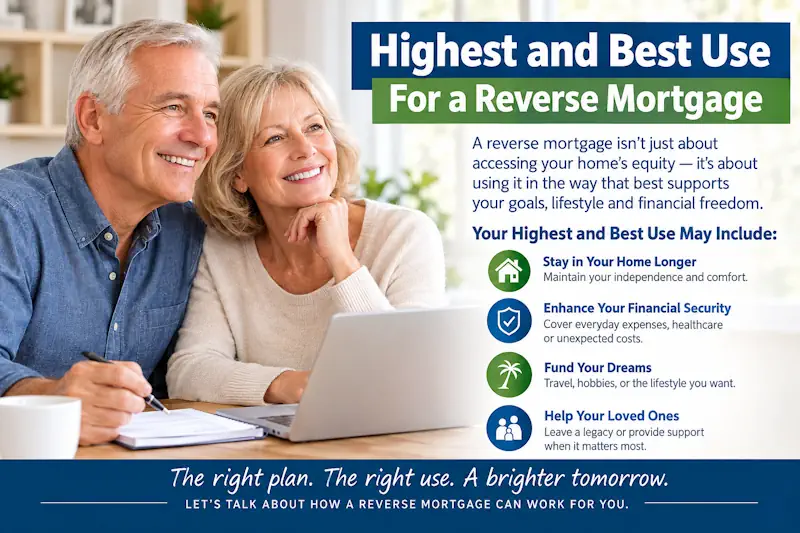
A reverse mortgage could potentially provide funds for:
- • Travel
- • Home improvements
- • Experiences with family
- • Hobbies
- • Helping children and grandchildren
- • Charitable giving
- • Creating an emergency reserve
- • Supplementing monthly retirement income
The goal isn’t to spend irresponsibly. It’s to recognize that your wealth is supposed to serve your life—not merely appear on a balance sheet.
4
Give With a Warm Hand Instead of a Cold Hand
Many parents intend to leave an inheritance to their children or grandchildren. But think about when your family may need your help the most. Is it when they’re 60 years old and you’re gone? Or could $25,000 today help a 30-year-old child purchase their first home?
Could helping pay a grandchild’s education expenses reduce or eliminate years of student-loan payments? Could assistance with starting a business change someone’s future? Could you make a meaningful gift to your church or favorite charity and actually see the impact of your generosity?
Accessing home equity may allow some families to begin transferring part of their wealth during their lifetime. I call this: Giving with a warm hand instead of a cold hand.
You get to participate. You get to see what your generosity accomplishes. And your family receives help when it may make the greatest difference.
* Gift and estate-tax consequences should always be reviewed with your tax and estate-planning professionals.
5
Shift Some Medical and Long-Term-Care Risk
One of the greatest financial uncertainties in retirement is future healthcare and long-term-care expenses. What if instead of simply setting aside a large pool of your own assets to absorb that risk, you investigated whether some of the risk could be transferred to an insurance company?
For an appropriate homeowner, one strategy worth exploring may be using a portion of reverse mortgage proceeds to help fund a properly designed life insurance policy that includes living benefits or a long-term-care rider. Depending on the policy, underwriting and rider provisions, benefits may potentially be available following qualifying chronic, critical or long-term-care events.
That can accomplish two potential objectives:
- Provide financial protection while you’re alive.
- Provide a death benefit to beneficiaries when you die.
This isn’t appropriate for everyone. Insurance costs, health underwriting, age, policy structure, benefit triggers and the cost of borrowing through a reverse mortgage all matter. But for the right person, it raises an important planning question:
“Should I retain all of this risk myself—or should I explore transferring some of it?”
6
Potentially Leave More to Your Heirs
At first glance, this sounds counterintuitive: “If I use some of my home equity, won’t there be less home equity left for my children?”
Possibly. A reverse mortgage is a loan. Interest and applicable mortgage insurance accrue, and using home equity reduces the equity that would otherwise remain, all else being equal. But your home isn’t your only asset. The better question is: “What happens to my entire estate?”
If strategically using home equity allows you to preserve other assets longer, avoid selling investments at unfavorable times, or acquire life insurance that ultimately pays a death benefit, the overall result can be very different from simply looking at the future equity in the house.
That’s why this should be evaluated as an overall wealth strategy, not simply a mortgage transaction.
7
Potentially Pay Less to Uncle Sam
Reverse mortgage proceeds are generally loan advances, not taxable income. That’s different from withdrawing money from a traditional IRA or 401(k), where distributions are generally included in taxable income.
That doesn’t mean a reverse mortgage automatically reduces your taxes. But having another source of cash may give you and your tax professional greater flexibility in determining which assets to draw from and when. That could be particularly useful when managing issues such as taxable retirement distributions, Roth conversions, capital gains, Social Security taxation, Medicare IRMAA exposure and required minimum distributions.
8
Put the Right Estate Plan Around Everything
Accessing home equity is only one piece of the puzzle. If your goal is to efficiently transfer wealth to the people and organizations you care about, your estate documents matter too.
Depending on your circumstances and state law, an estate-planning attorney may recommend a revocable living trust or another estate-planning structure to help manage your assets and potentially avoid probate for assets properly titled or otherwise covered by the plan.
A reverse mortgage shouldn’t replace estate planning. It should fit within it.
Think of Your Home Equity as Part of Your Retirement Portfolio
Here’s the bigger idea. Instead of thinking: House over here. Investments over there. Insurance somewhere else. Estate plan in another drawer… bring the pieces together.
For the right homeowner, a coordinated strategy could look something like this:
Home Equity → Liquidity
Use a reverse mortgage to make a portion of home equity available.
Liquidity → Flexibility
Use those funds strategically for living expenses, emergencies, family gifts or other retirement needs.
Flexibility → Investment Preservation
During unfavorable markets or strategic tax years, consider using available home equity rather than automatically liquidating investments.
Liquidity → Risk Transfer
When appropriate, investigate using some proceeds to fund insurance with living benefits or long-term-care protection.
Insurance → Legacy
A properly structured policy may provide benefits during life and potentially leave a death benefit to beneficiaries.
Estate Planning → Efficient Transfer
Coordinate your trust, beneficiaries and other estate-planning documents with an experienced attorney.
The objective isn’t to maximize one asset. The objective is to make your entire financial picture work together.
Don’t Start With the Reverse Mortgage. Start With the Goal.
The first question shouldn’t be: “How much can I borrow?”
“What do I want my money to accomplish during the rest of my life?”
Then determine whether your home equity should be part of the solution.
A reverse mortgage isn’t appropriate for everyone. Life insurance isn’t appropriate for everyone. A trust isn’t appropriate for everyone. But when these tools are appropriate and thoughtfully coordinated, they can create something many retirees value tremendously: More choices.
Kevin Guttman, CRMP, CHEA
Senior Mortgage Broker & Reverse Mortgage Specialist
C2 Financial | NMLS #384936